Compact Finite Differences
Added in version 0.13.
Compact (or implicit) finite differences achieve spectral-like resolution with small stencils by coupling derivative approximations at neighboring grid points. The classical reference is Lele (1992).
Background
Standard (“explicit”) finite differences express a derivative as a weighted sum of function values:
Compact finite differences generalize this by including derivative values on the left-hand side:
The classic tridiagonal case uses \(\alpha_{-1} = \alpha_1 = 1/3\) and five function values. Despite needing only nearest neighbors, this scheme reaches 6th-order accuracy — the same as a 7-point explicit stencil.
The price is that computing the derivative requires solving a banded linear system. For a tridiagonal left-hand side this costs \(O(N)\) and is fast in practice.
Usage
There are two ways to set up a compact scheme.
Explicit scheme definition — pick the left-hand side coefficients (\(\alpha\)) and right-hand side offsets, and findiff solves for the matching \(c_k\):
import numpy as np
from findiff import Diff, CompactScheme

x = np.linspace(0, 2 * np.pi, 100, endpoint=False)
dx = x[1] - x[0]

# Lele (1992) tridiagonal scheme, Section 2.1.1
scheme = CompactScheme(
    deriv=1,
    left={-1: 1/3, 0: 1, 1: 1/3},
    right=[-3, -2, -1, 0, 1, 2, 3],
)

d_dx = Diff(0, dx, scheme=scheme, periodic=True)

f = np.sin(x)
df = d_dx(f)            # 6th-order accurate
Shortcut — let findiff choose a scheme that meets a target accuracy:
d_dx = Diff(0, dx, compact=3, acc=6, periodic=True)
The compact parameter sets the number of left-hand side points (must be an
odd integer). findiff determines the left-hand side \(\alpha_k\) and the
right-hand side \(c_k\) jointly, so that the accuracy order is maximal for
the given stencil widths (Lele, 1992), and uses the narrowest right-hand side
stencil that reaches the requested accuracy. This yields the classical schemes,
for example:
Parameters |
Left-hand side |
Right-hand side |
|---|---|---|
|
\(\alpha_1 = 1/4\) (Padé) |
3 points |
|
\(\alpha_1 = 1/3\) |
5 points |
|
\(\alpha_1 = 4/9,\ \alpha_2 = 1/36\) |
5 points |
|
\(\alpha_1 = 1/2,\ \alpha_2 = 1/20\) |
7 points |
As with explicit finite differences, acc is the minimum accuracy order;
the scheme may be more accurate if no narrower stencil exists.
Higher derivatives
Use the ** operator:
d2_dx2 = d_dx ** 2
This automatically constructs a new compact scheme for the second derivative with matching accuracy.
Spectral-like resolution
Added in version 0.15.
The schemes above spend all free parameters on the accuracy order. Lele’s spectral-like schemes impose only a moderate order and use the remaining parameters to resolve short waves better. This pays off for multi-scale problems (turbulence, shocks, the Burgers equation), where the solution contains wavelengths of only a few grid points.
d_dx = Diff(0, dx, compact=5, acc=4, spectral=True, periodic=True)
d2_dx2 = d_dx ** 2          # also spectrally optimized
With spectral=True the right-hand side has compact + 2 points. For full
control, construct the scheme directly:
scheme = CompactScheme.spectral(deriv=1, num_left=5, num_right=9, acc=6)
d_dx = Diff(0, dx, scheme=scheme, periodic=True)
The accuracy order acc is imposed exactly; the remaining coefficients minimize
the error of the modified wavenumber in the least-squares sense on
\([0, w_{max}]\). By default, \(w_{max}\) is chosen to maximize the
resolving efficiency: the fraction of \([0, \pi]\) in which the relative
error of the modified wavenumber stays below tol (default 1e-3). Pass
max_wavenumber to fix the range instead. Both quantities are available for
any scheme:
scheme.modified_wavenumber(w)      # w' for scaled wavenumbers w = k h
scheme.resolving_efficiency(1e-3)  # e.g. 0.56 -> 0.70 for compact=5, 7 points
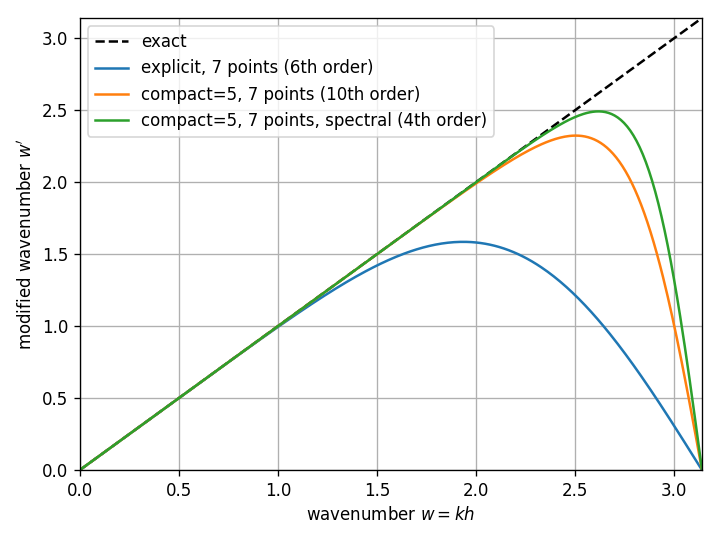
The trade-off: for well-resolved, smooth functions a scheme of maximal order is more accurate, while the spectral scheme wins for short waves. On non-periodic grids, the boundary closures (which have maximal order) dominate the error for short waves within the first few grid points.
Non-periodic boundaries
For non-periodic grids the interior stencil extends past the boundary at the first and last few grid points. findiff handles this with one-sided compact stencils (Visbal & Gaitonde, 2002): the left-hand side alphas and right-hand side offsets are restricted to points that exist, and the system is re-solved for the boundary rows. Since one-sided stencils lack the symmetry of the interior scheme, the right-hand side stencil is widened at the boundary until it reaches the interior accuracy order (as far as the grid size permits).
x = np.linspace(0, 1, 100)
dx = x[1] - x[0]

d_dx = Diff(0, dx, scheme=scheme, periodic=False)
df = d_dx(np.sin(x))
Non-uniform grids
Added in version 0.15.
Pass the coordinates instead of the spacing, as for explicit differences:
x = (1 - np.cos(np.pi * np.linspace(0, 1, 100))) / 2   # clustered at both ends

d_dx = Diff(0, x, compact=3, acc=6)
df = d_dx(np.sin(x))
d2_dx2 = d_dx ** 2
The left-hand side keeps the \(\alpha_k\) of the uniform scheme, which keeps
the banded system well-conditioned on any grid. The right-hand side coefficients
are solved row by row from the actual grid spacings. Without the symmetry of a
uniform grid, the right-hand side needs acc + deriv points (rounded up to an
odd number) to reach accuracy order acc, so the stencil is as wide as for
explicit differences. The benefit of the compact scheme on non-uniform grids is
therefore a smaller error constant rather than a narrower stencil. The scheme
reproduces polynomials of degree up to the stencil width minus one exactly on
any grid.
Multi-dimensional grids
Compact differentiation extends to N-dimensional arrays via Kronecker products:
x = y = np.linspace(0, 2 * np.pi, 100, endpoint=False)
dx = x[1] - x[0]
X, Y = np.meshgrid(x, y, indexing='ij')

d_dx = Diff(0, dx, compact=3, acc=6, periodic=True)
d_dy = Diff(1, dx, compact=3, acc=6, periodic=True)

f = np.sin(X) * np.cos(Y)
laplacian = (d_dx**2 + d_dy**2)(f)
You can freely mix compact and standard finite difference operators in the same expression.
Matrix representation
The matrix form of a compact operator is \(L^{-1} R\). Obtain it with
the usual matrix() call:
M = d_dx.matrix((100,))
df = M.dot(f)
Note that inverting the banded \(L\) introduces fill-in, so the matrix is denser than for explicit finite differences: each row couples all points on its grid line along the differentiation axis. On an \(n \times n\) grid the matrix therefore has \(n^3\) non-zero entries.
Limitations
Periodic non-uniform grids are not supported (as for explicit differences).
The
stencil()method is not supported for compact schemes.estimate_error()does not support compact schemes and raises an error.Compact schemes run on NumPy / SciPy only. JAX or CuPy arrays are converted to NumPy arrays (see GPU / JAX / CuPy).
The grid must have at least as many points along the differentiation axis as the stencil reaches away from a point; otherwise a
ValueErrorexplains the required size.
References
S. K. Lele, “Compact Finite Difference Schemes with Spectral-like Resolution”, J. Comp. Phys. 103, 16-42 (1992).
M. R. Visbal and D. V. Gaitonde, “On the Use of Higher-Order Finite-Difference Schemes on Curvilinear and Deformed Meshes”, J. Comp. Phys. 181, 155-185 (2002).